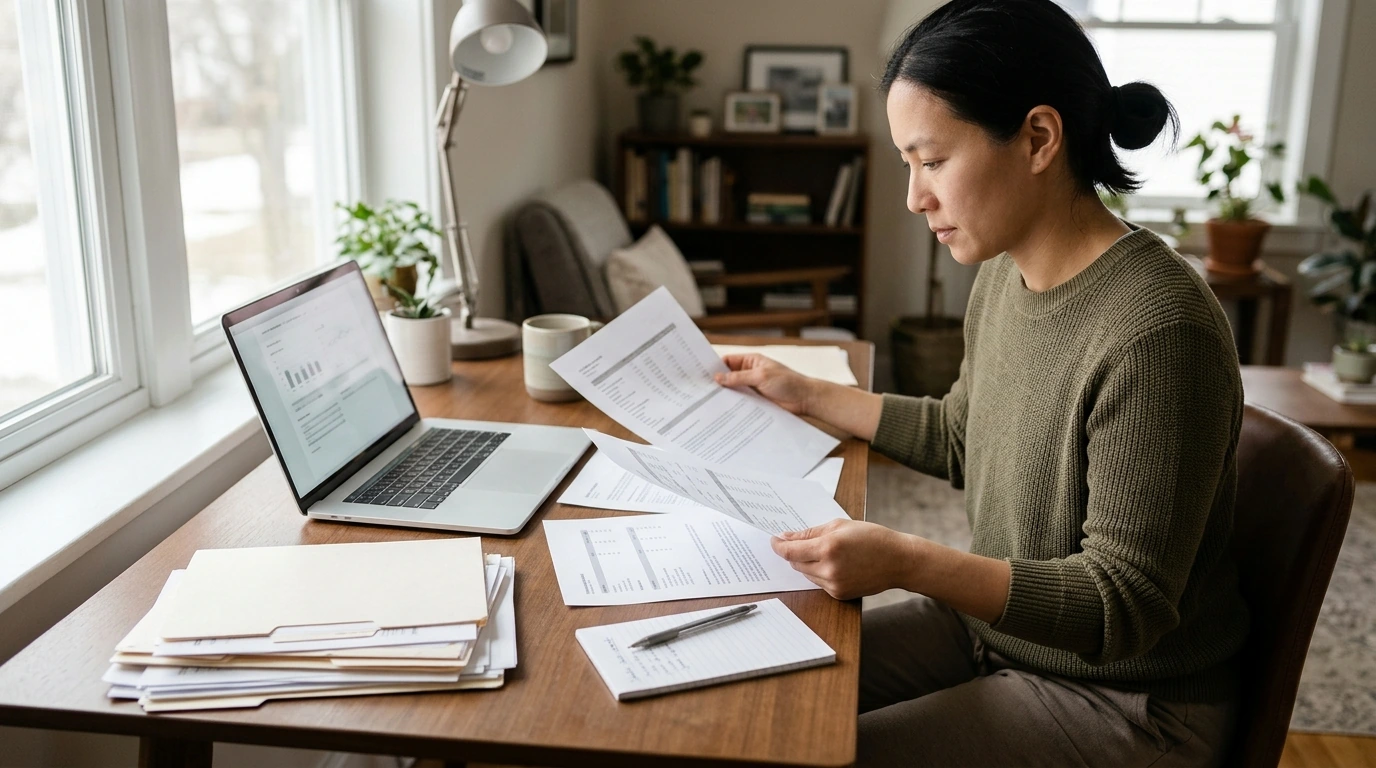
Your credit history can feel complicated until you break it into a few manageable steps. Start by getting your reports, reading what they say, and deciding whether anything needs attention. You do not need to understand every credit-scoring formula to build a useful routine.
A credit report records information such as your credit accounts and payment history. A credit score is a number calculated from information in a credit report. Reading the report helps you see the details behind a score—and spot information that may need a closer look.
If you are in the U.S., request your reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com. The three reports may not contain identical information, so review each one. Checking your own report does not lower your credit score.
Save each report securely and note when you reviewed it. You can then work through one report at a time rather than trying to compare every line at once.
| Look at | Check for | Next step |
|---|---|---|
| Personal information | Names or addresses you do not recognize | Make a note and investigate unfamiliar details |
| Accounts | Balances, limits, or accounts that are not yours | Compare entries with your own records |
| Payment history | Late payments you believe were reported incorrectly | Gather statements or payment confirmations |
| Inquiries | Credit applications you do not recognize | Investigate and consider fraud-protection steps |
Most reports group information into recognizable sections: identifying information, accounts, payment history, and inquiries. You may also see collections or public-record information. First, look for anything you cannot connect to your own records. Then separate entries that need an explanation from those you have reason to believe are wrong.
For example, an old address may still be associated with you. A creditor may appear under a business name different from the name on your card or statement. Neither detail automatically means there is an error or fraud. Compare the dates, account numbers where shown, and other available details before deciding what to do.
If an account appears on more than one report, compare how each credit reporting company lists it. Write down the company showing the entry, the account details, and your specific concern. A note such as “May payment shown as late; bank confirmation shows payment on May 12” is more useful for follow-up than “payment history looks wrong.” Our team favors keeping that short list separate from your saved reports so you can find it when you need it.
Dispute information you believe is inaccurate with each credit reporting company that shows it. You can also contact the business that supplied the information. The Consumer Financial Protection Bureau explains both routes and offers guidance on credit reports and scores.
Be precise: identify the entry, describe the error, and say what correction you are requesting. Include copies of relevant statements or payment confirmations when appropriate, and keep copies of what you send and any replies. That record makes it easier to track what you have already done.
If an account may be connected to identity theft, use IdentityTheft.gov to make a recovery plan. An unfamiliar entry is a reason to investigate, not proof by itself that someone has stolen your identity.
Once you have addressed possible errors, focus on actions you can control: pay bills on time, keep credit-card balances manageable, and consider whether you need new credit before applying. Review account statements so you can catch a problem while the details are still easy to find.
Set realistic expectations, too. Accurate negative information generally cannot be removed simply because it lowers a score. Correcting a genuine error matters, but no particular score change or timeline is guaranteed. A practical routine is to revisit your reports periodically and review your plan when your finances change—for example, after opening an account or paying off a debt.
If you want a companion while learning this process, our Your Credit Compass digital guide offers a way to keep your questions and next steps approachable. It does not replace your official credit reports or promise a particular score increase. You will get more from it once you have identified what you want to understand about your own reports.
Choose tools based on the task in front of you. The credit guide is relevant if you want help organizing what you are learning; it is not necessary just to request a report or file a dispute. If a comfortable listening setup helps you concentrate while you review records, our in-ear headphones are another available option—but they are not a credit tool, and you do not need them to take any of the steps above.
No. Requesting or reviewing your own report is not a credit application and does not lower your score.
Not every lender reports to every credit reporting company, and updates may appear at different times. Review each report on its own merits.
There is no guaranteed quick fix. Correcting genuine errors and practicing sound credit habits can help over time, but results vary.

Leave a comment